VA Home Loan Benefits: Why Today's Housing Market Could Favor Veteran Homebuyers

VA Home Loan Benefits: Why Today's Housing Market Could Favor Veteran Homebuyers
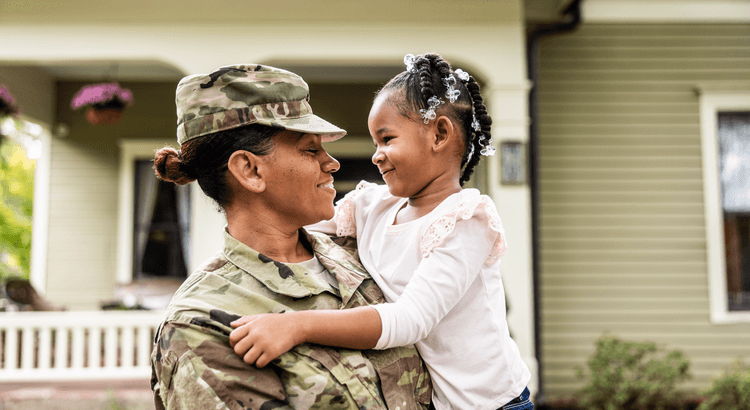
If you're a veteran or active-duty service member who's been hoping to buy a home, you may have more going for you in today’s housing market than you realize.
VA home loans already come with some pretty powerful benefits. But now, with more homes for sale and buyers having more room to negotiate in many markets, those benefits could go even further.
And if you've ever heard that buying with a VA loan is harder, takes longer, or puts you at a disadvantage, there's something else you should know… a lot of what people believe about VA loans simply isn't true.
What Are the Benefits of VA Home Loans for Veterans?
According to an August 2025 announcement from the Department of Veterans Affairs (VA), nearly 4 million service members and veterans had active VA-guaranteed home loans. And it's easy to see why.
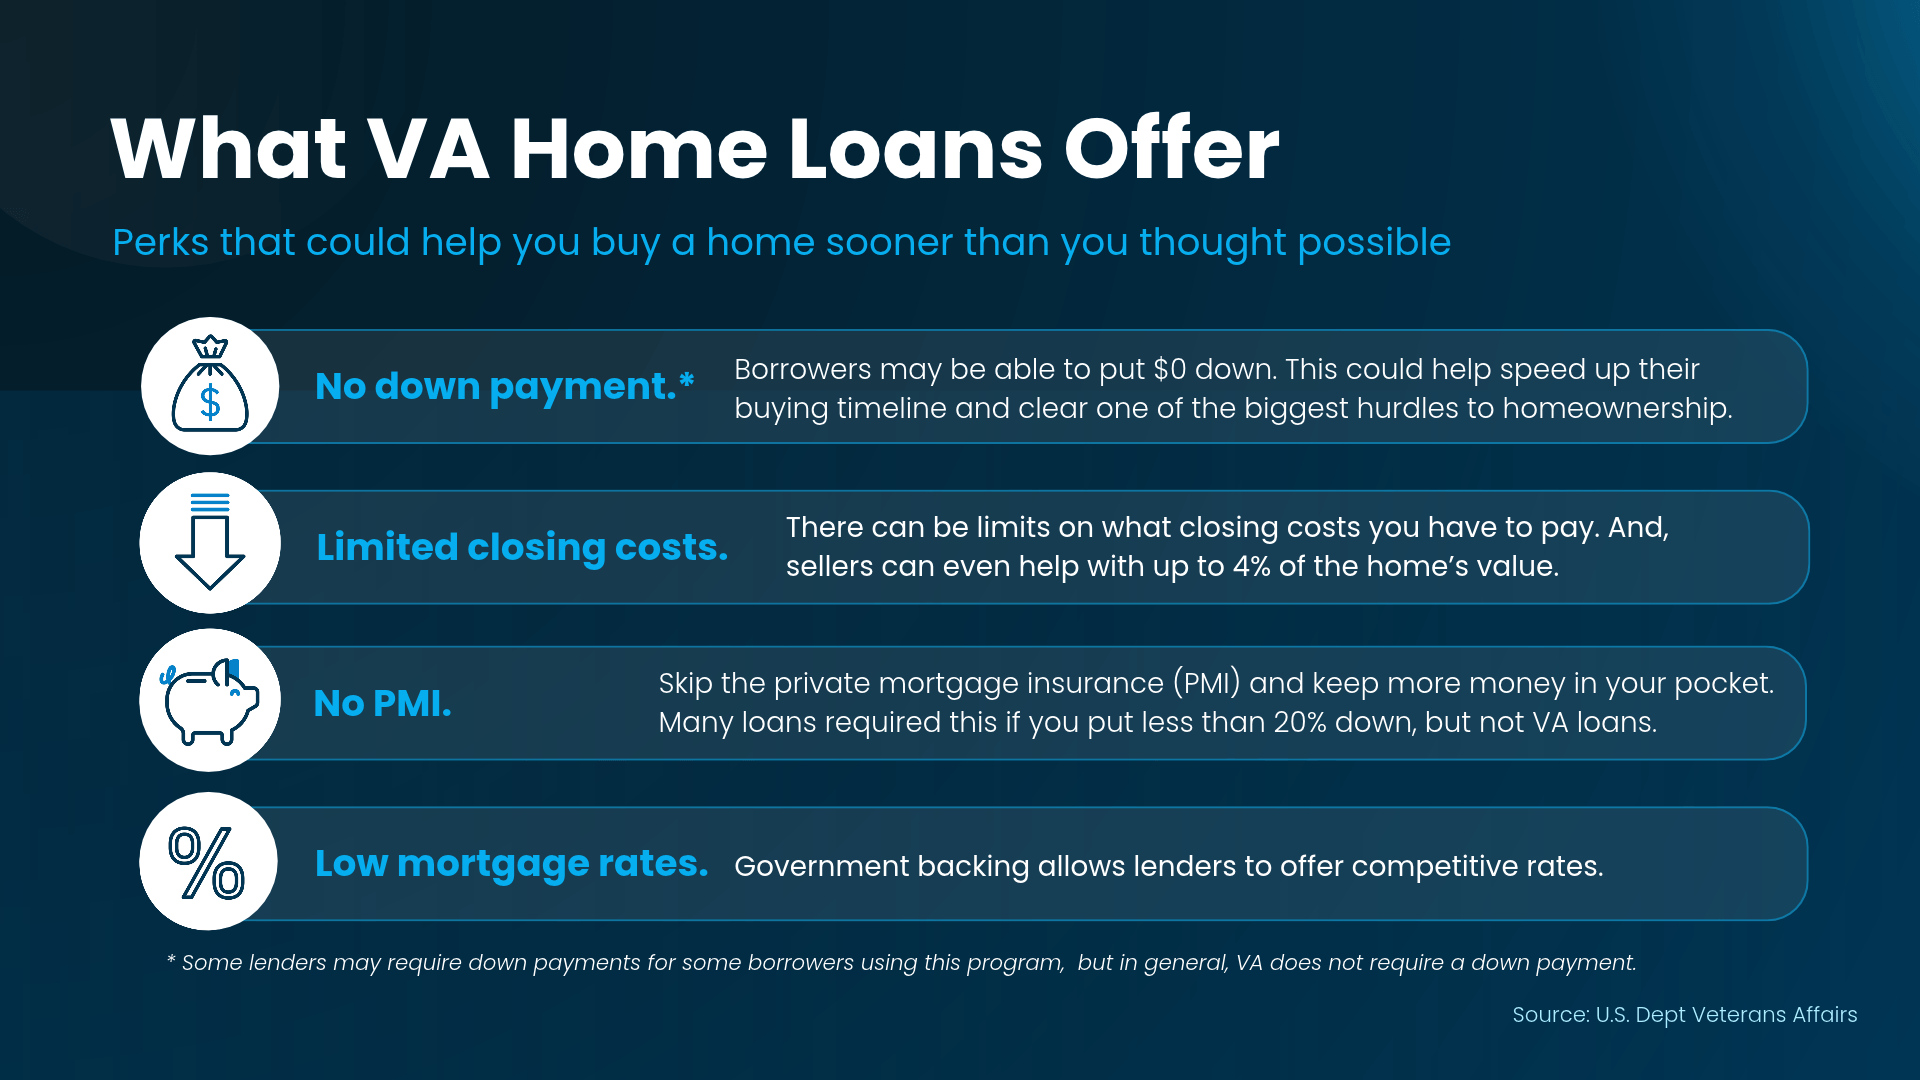
For eligible veterans and service members, VA loans offer advantages that can make buying a home more affordable, including:
- No down payment required for many eligible borrowers.
- No monthly mortgage insurance, even with no down payment.
- Competitive mortgage rates that can help lower monthly payments.
Benefits like this are powerful in any market – and even more so today. That may be why VA loan usage has grown for the last two years in a row.
Why Today's Housing Market Could Be Different for VA Homebuyers
A few years ago, when homes were getting multiple offers and buyers were competing for nearly every listing, VA buyers sometimes had a harder time getting their offers accepted.
A 2021 survey from the National Association of Realtors (NAR) found 89% of sellers were likely to accept an offer from a buyer using a conventional loan. But only 30% were likely to accept one using an FHA or VA loan.
The reason? Some sellers were concerned that VA financing would take longer, be more difficult to close, and require them to pay more in costs and repairs. But those concerns don't necessarily reflect how VA loans actually perform.
VA Home Loan Myths vs. Facts: Approval, Appraisals, and Closing Costs
A white paper from Vetted VA based on 2025 mortgage data busted a lot of VA loan myths:
Myth #1: VA loans get denied more often than other loans.
- The Reality: VA purchase loans had the lowest denial rate. Just 8.2% of VA purchase applications were denied, compared to 15.0% for conventional loans, 12.8% for FHA loans, and 12.5% for USDA loans.
Myth #2: VA financing is less reliable.
- The Reality: 90% of VA home loan applications that reached underwriting made it to closing, compared to 81% for conventional loans.
Myth #3: VA appraisals take longer.
- The Reality: VA loan appraisals typically take 7–10 business days, similar to conventional and FHA loans.
Myth #4: Sellers have to pay all the closing costs for VA buyers.
- The Reality: VA buyers can pay many standard closing costs themselves. Buyers and sellers can also negotiate which eligible costs the seller will cover.
How VA Homebuyers May Negotiate Home Prices and Closing Costs
Since there are more homes for sale and fewer buyers competing in many areas, sellers may be more open to different financing options than they were a few years ago. And the opportunity doesn't stop at getting your offer accepted.
Depending on the house and your local market, you may also be able to negotiate a lower price, ask for repairs, or request help with closing costs.
VA guidelines generally allow sellers to pay certain buyer closing costs. Specific seller concessions are subject to a 4% limit under VA rules, while many customary closing costs are treated separately.
Think about what that combination could mean. You may be able to buy with no down payment, avoid mortgage insurance, and negotiate help with some of the other expenses that come with buying a home.
That could mean keeping thousands of dollars in your savings instead of spending them upfront, giving you more breathing room after you get the keys.
Bottom Line: How VA Loan Benefits and Today's Housing Market Could Work Together
If you're active duty, you've served, or you know someone who has, connecting with a local real estate agent and a trusted VA-approved lender can help you understand your homebuying options and financing eligibility.
Your VA home loan benefits and today's housing market could be a powerful combination, especially in areas where buyers have more opportunities to negotiate.
If you're considering buying or selling a home in North County San Diego, here are a few helpful resources to plan your next move:
Search Homes – Explore available homes for sale in Oceanside, Carlsbad, Vista, San Marcos, Escondido, and surrounding communities.
Mortgage Calculator – Estimate potential monthly mortgage payments based on your purchase price, down payment, and interest rate.
Market Snapshot – Explore local housing market trends, including home prices, inventory, and market activity.
Home Value – Get an estimate of your current home's value if you're considering selling before buying.
Contact Us – Connect with a local real estate professional to discuss your homebuying goals and available properties.
Understanding your VA loan benefits, exploring available homes, and reviewing local market conditions can help you make a more informed decision about your next move.
Frequently Asked Questions About VA Home Loans
1. Can veterans buy a home with no down payment using a VA loan?
Yes. Many eligible veterans, active-duty service members, and qualifying surviving spouses may be able to purchase a home with no down payment through a VA-backed home loan. However, eligibility, lender requirements, and property appraisal considerations apply. Buyers should also budget for closing costs and any applicable VA funding fee, unless exempt. A VA-approved mortgage lender can help determine individual qualification requirements.
2. What are the benefits of a VA home loan compared to a conventional loan?
VA home loans offer several potential advantages, including no down payment for many eligible borrowers, no monthly mortgage insurance, and competitive interest rates. Unlike many conventional loans with low down payments, VA loans do not require monthly mortgage insurance. Actual interest rates, closing costs, and loan terms vary by lender and borrower qualifications.
3. Can VA homebuyers negotiate home prices and closing costs in today's housing market?
Yes. VA homebuyers can negotiate purchase prices, request repairs, and ask sellers to contribute toward allowable closing costs, just like other buyers. In markets with more homes for sale and less buyer competition, sellers may be more willing to negotiate. However, opportunities depend on local housing conditions, the property, and the seller. VA guidelines also place limits on certain seller concessions.
About the Agent: Patricia Villanueva – North County San Diego Real Estate Agent
Patricia Villanueva is a real estate agent helping homebuyers and sellers throughout North County San Diego, including Oceanside, Carlsbad, Vista, San Marcos, and Escondido.
Whether you're a first-time homebuyer, veteran looking to buy a home, or homeowner preparing to sell, Patricia Villanueva provides guidance with home searches, property showings, comparable sales, purchase offers, negotiations, and listing preparation and marketing.
Looking to buy or sell a home in North County San Diego? Contact Patricia Villanueva to discuss your real estate goals.
Disclaimer: This article is for general informational purposes only and does not constitute financial, mortgage, legal, or tax advice. VA home loan eligibility, terms, and requirements vary by borrower, lender, and property. Housing market conditions, prices, and negotiating opportunities vary by location and may change over time. Consult a qualified mortgage lender for financing information and appropriate licensed professionals for advice specific to your circumstances.
Categories
- All Blogs (187)
- 55+ Communities (1)
- Buyer & Seller Resources (38)
- Buyers (12)
- Condo Living (2)
- First-Time Buyers (50)
- Foreclosure Trends (2)
- Foreclosure Updates (2)
- Home Buying Tips (83)
- Home Equity (1)
- Home Improvement (1)
- Home Selling Tips (62)
- Homebuyer Tips (51)
- Homeowner Tips (31)
- Housing Market Insights (32)
- Housing Market Trends (60)
- Market Updates (28)
- Mortgage Education (16)
- Mortgage Insights (15)
- Mortgage Rates (5)
- New Construction (7)
- Pricing Strategy (3)
- Real Estate Advice for Buyers (48)
- Real Estate Advice for Sellers (44)
- Real Estate Insights (23)
- Real Estate Investing (1)
- Real Estate Market Updates (68)
- Renting vs. Owning (4)
- Retirement Planning (2)
- Seller Resources (19)
- Sellers (19)
- VA Home Loans (1)
Recent Posts