Mortgage Rates for Homebuyers: Why the Rate You See Online May Not Be the Rate You Get
Mortgage Rates for Homebuyers: Why the Rate You See Online May Not Be the Rate You Get
You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that's left you reluctant to buy a home, here's what you need to remember…
That's not necessarily the number you'd get.
It's a common misconception that the rate you see in the headlines is the same one you'd get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about.
What Determines the Mortgage Rate You May Qualify For?
Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that.
That’s why a lender can help you understand the mortgage rate and financing options that may be available based on your individual circumstances. When evaluating your mortgage application and financing options, a lender may consider factors such as:
- Your credit score: Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate.
- Your debt-to-income ratio (DTI): This compares your monthly debt payments with your monthly income before taxes. Lenders may consider your existing debts and income when evaluating your mortgage application and financing options.
- Your down payment and loan-to-value (LTV) ratio: Your down payment is the amount of the home's purchase price you pay upfront. LTV compares the amount you're borrowing with the value of the property.
- Your loan type and loan term: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs.
Even after you find a home you love, other things can have an impact too. For example:
- A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy.
- Seller concessions: Depending on the loan program and transaction, a seller may be able to contribute toward certain buyer closing costs or prepaid expenses, subject to lender and loan program requirements. Ask your lender how seller concessions may apply to your specific financing.
There’s a lot that can ultimately have an impact on your actual rate.
Why Mortgage Pre-Approval Matters for Homebuyers
If you want to know if your number could be higher or lower than the headlines on social, talk to a loan officer. A conversation with a loan officer can help you better understand your financing options, how much you may be able to borrow, and the mortgage rates and terms that may be available based on your circumstances.
Your lender may discuss pre-qualification or pre-approval with you:
- Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information.
- On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information.
Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why:
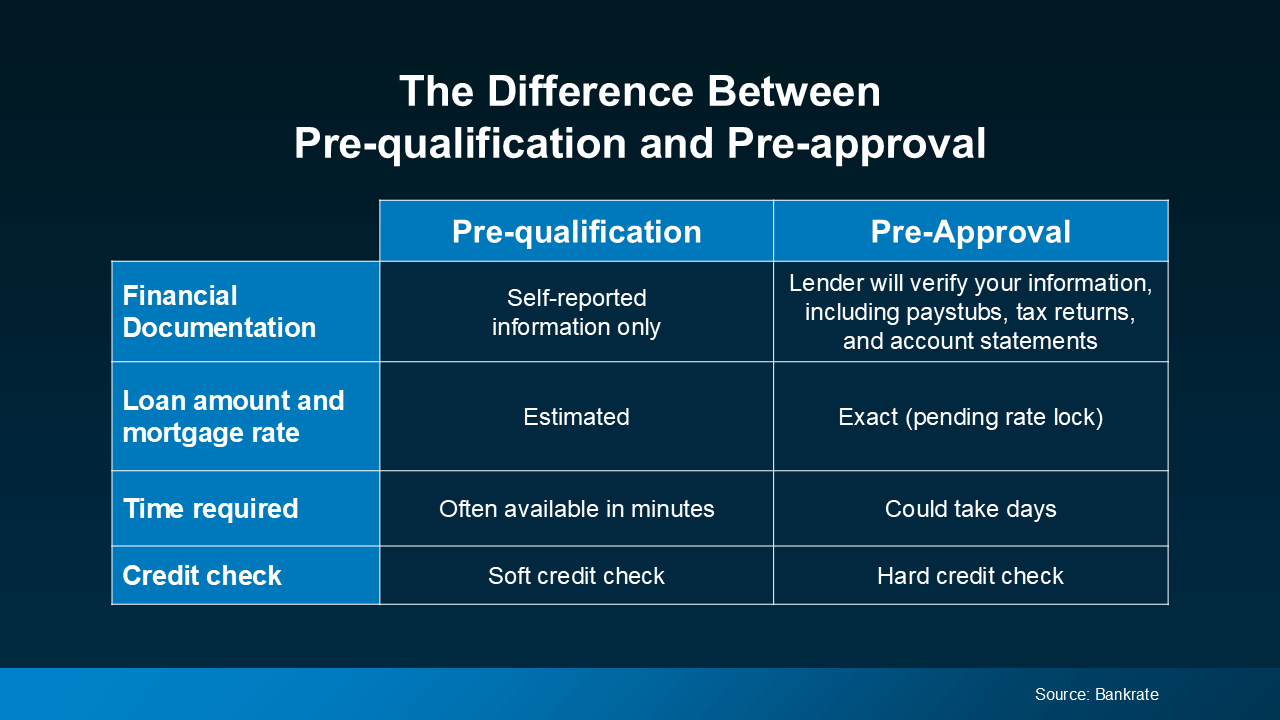
Note: Lenders may use the terms pre-qualification and pre-approval differently, so ask your lender what each process involves and what documentation is required.
Questions To Ask Your Lender Before Buying a Home
Ask your lender what documents you’ll need to gather for that conversation. And keep these questions in your pocket too. They’re good things to go over when you talk:
- What will I gain or lose by waiting to buy a home for 3, 6, or 12 months?
- Will I get any tax advantages by buying a home - and what are they?
- What's the benefit of buying a home and starting to build equity now versus waiting? And how does that impact my finances in the long run?
- How will rate changes in either direction affect me?
Once you better understand your financing options, maybe you can buy now. Or maybe you still need to wait. But at least you’ll have more information to help you make an informed decision.
Buying a Home in North San Diego County?
If you’re considering buying a home in North San Diego County, mortgage rates are only one part of the homebuying picture. Your financing options depend on your individual circumstances, so a licensed loan professional can help you understand the mortgage programs, rates, and terms that may be available to you.
I can help you understand the North San Diego County real estate market, explore available homes, and navigate the homebuying process in Vista, Oceanside, San Marcos, Escondido, Fallbrook, Bonsall, Carlsbad, and surrounding communities.
Ready to explore your options? Search homes for sale in North San Diego County, check the latest market snapshot, or use the mortgage calculator to estimate potential mortgage payment scenarios.
Already own a home? Get an estimated home value to learn more about your property's current market position.
Have questions about buying or selling a home in North San Diego County? Contact me to start a conversation.
Frequently Asked Questions About Mortgage Rates and Homebuying
Is the mortgage rate I see online the rate I’ll actually get?
Not necessarily. Online and advertised mortgage rates can provide a general picture of the market, but the rate available to an individual borrower can vary. Factors such as your credit profile, down payment, loan type, loan term, and other financial and loan details can affect the rates and financing options a lender offers. A licensed loan professional can provide information based on your specific circumstances.
What factors can affect the mortgage rate available to a homebuyer?
Several factors may affect mortgage rates and loan costs, including your credit score, down payment, loan amount, loan type, loan term, and interest rate type. Because mortgage options vary by borrower and lender, homebuyers should speak with a licensed loan professional about the rates and programs that may be available based on their individual circumstances.
What is the difference between mortgage pre-qualification and pre-approval?
The terms pre-qualification and pre-approval can vary by lender. Some lenders may offer a pre-qualification based on information you provide and a pre-approval based on information they verify, but lender processes differ. Neither should automatically be considered a guaranteed loan offer. Ask your licensed loan professional what their pre-qualification or pre-approval process involves.
About the Agent: Patricia Villanueva
Patricia Villanueva is a North San Diego County real estate agent helping buyers and sellers navigate the local housing market. Serving Vista, Oceanside, San Marcos, Escondido, Fallbrook, Bonsall, Carlsbad, and surrounding communities, Patricia Villanueva assists clients with buying a home, selling a home, searching for homes for sale, understanding local market conditions, and navigating real estate transactions.
Whether you're a first-time homebuyer, relocating to North San Diego County, searching for your next home, or considering selling, contact Patricia Villanueva to discuss your real estate goals.
Disclaimer: This content is for general informational purposes only and is not intended as financial, lending, tax, or legal advice. Mortgage rates, loan programs, qualification requirements, and terms vary by borrower and lender and are subject to change. Consult a licensed mortgage professional regarding your financing options and qualified tax or legal professionals regarding your individual circumstances. Real estate market conditions and property information may also change. Information is deemed reliable but is not guaranteed.
Categories
- All Blogs (173)
- Buyer & Seller Resources (32)
- Buyers (9)
- Condo Living (1)
- First-Time Buyers (46)
- Foreclosure Trends (2)
- Foreclosure Updates (2)
- Home Buying Tips (73)
- Home Equity (1)
- Home Improvement (1)
- Home Selling Tips (56)
- Homebuyer Tips (47)
- Homeowner Tips (27)
- Housing Market Insights (32)
- Housing Market Trends (59)
- Market Updates (28)
- Mortgage Education (16)
- Mortgage Insights (13)
- Mortgage Rates (3)
- New Construction (6)
- Pricing Strategy (3)
- Real Estate Advice for Buyers (41)
- Real Estate Advice for Sellers (39)
- Real Estate Insights (22)
- Real Estate Investing (1)
- Real Estate Market Updates (56)
- Renting vs. Owning (4)
- Retirement Planning (1)
- Seller Resources (18)
- Sellers (18)
- VA Home Loans (1)
Recent Posts